The Class Action Wave May Be Approaching

By Steven D. Ginsburg and Kenneth B. Franklin

The Consumer Finance Protection Bureau (“CFPB”) recently announced that it was considering a rule that would ban consumer financial companies from using arbitration clauses in their customer agreements to block class action lawsuits. According to a study by the CFPB, financial institutions often rely on arbitration clauses to block group lawsuits. The CFPB took issue with this practice because it claims that very few consumers were aware of the arbitration clauses or understood what they meant. As a result, either because of ignorance or an unwillingness to pursue individual grievances, the CFPB found that even though millions of consumers would be entitled to relief through group settlements, very few individual customers actually seek relief through arbitration.

With these findings in mind, the CFPB initiated the process to implement a regulation that would prohibit finance companies from including arbitration clauses that would preclude class action lawsuits in their consumer agreements. The new rule would encompass most of the consumer financial products the CFPB regulates, including credit cards, checking and deposit accounts, prepaid cards, money transfer services, some auto loans, auto title loans, payday loans, private student loans and installment loans. Arbitration clauses are already prohibited in consumer mortgages under the Dodd-Frank Act.

The CFPB does not propose banning arbitration clauses from consumer finance agreements all together. Rather, arbitration clauses would be permissible as long as they explicitly allow cases to be filed as class actions unless and until the class certification is denied by the court, or the class claims are dismissed in court. Financial companies would also have to submit any initial arbitration claim filings and awards issued to the CFPB to “ensure” the fairness of the arbitration process.

Although the CFPB is still in the early stages of considering this rule change, our clients should carefully monitor the progress of this new rule and, if appropriate, voice any concerns they may have with the new rule when the CFPB solicits public comments.

More information about the CFPB’s proposed new rule can be found at:
http://www.consumerfinance.gov/newsroom/cfpb-considers-proposal-to-ban-arbitration-clauses-that-allow-companies-to-avoid-accountability-to-their-customers/
The Check’s in the Mail

By Steven D. Ginsburg and Kenneth B. Franklin

In the consumer loan context, one issue that frequently arises between creditors and debtors is whether the debtor has made a timely payment on his or her account. Both the Truth in Lending Act (“TILA”) and Regulation Z, which implements TILA, speak to this issue, but appear to contradict each other when it comes to credit card accounts.

Continue reading “The Check’s in the Mail”

Banks Target Employee Behavior to Reduce Cyber Crime

As reported in the Wall Street Journal on December 21, banks are spending enormous sums on cybersecurity (Wells Fargo’s CEO John Stumpf says ‘It is the only expense where I ask if it’s enough’), and much of that is directed towards reducing risks from employees who unwittingly make it easier for hackers to breach a bank’s defenses. Employee error results in approximately 30% of data breaches, according to a survey released last month by the Association of Corporate Counsel. Banks in particular face substantial risk because they possess so much customer information, as well as huge sums of money.

Among the ways that cybercriminals gain access to protected data are out of office messages on work computers and phones , and vacation photos posted on social media ( which signal unmonitored computers ). A significant risk is posed by employees opening phishing emails, especially the increasingly sophisticated “spear phishing” emails, that appear to be requests from high-ranking bank officials. Many banks send employees simulated phishing attacks . The opening of one of these fake phishing emails may, for example, start a video to educate the employee on how they should have handled the situation.

These efforts are another indication that fighting cyber crime involves virtually all parts of an organization, not just the IT department.

Duane Morris Receives TD Bank U.S. Legal Champion Award

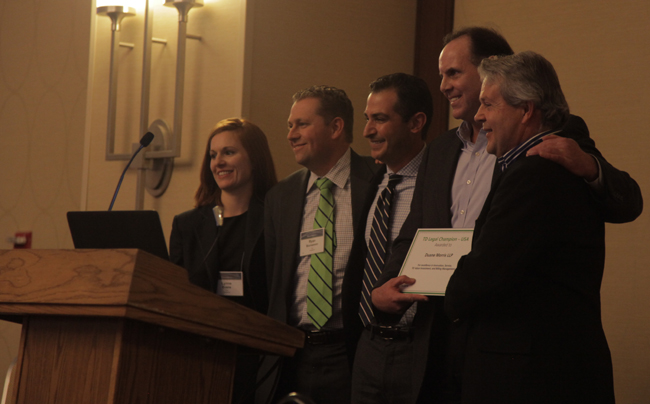
Duane Morris received the first TD Bank “U.S. Legal Champion” Award, recognizing TD Bank’s strategic law firms that provide valued work and high performance in the categories of innovation, service, TD value investment and billing management.

TD Bank deputy general counsel Leo Doyle presented the award to Duane Morris partner Alexander Bono at the trial practice group session at Duane Morris’ annual firm meeting.

TD Bank’s Leo Doyle presents U.S. Legal Champion Award to Duane Morris’ Lex Bono and the team (from left Lynne Evans, Ryan Borneman and Michael Zullo)

To learn more about this honor, which was reported on in the November 12, 2015, issue of The Legal Intelligencer, please visit the Duane Morris website.

Florida District Court Issues Key Ruling in Mortgage Foreclosure Case

Previously, Florida appellate courts were strictly enforcing the acceleration requirements in mortgages. In Gorel v. The Bank of New York Mellon, Case No. 5D13-3272 (Fla. 5th DCA May 8, 2015), a Florida appellate court has now held that the failure of a default notice to specify a date not less than 30 days by which the default must be cured does not constitute a valid defense where the defective notice did not prejudice the borrower, because he made no attempt to cure the default.

To read the full text of this Duane Morris Alert, written by Steven Ginsburg, please visit the Duane Morris website.


City of Philadelphia Requests Proposals to Implement Online Auction for Sale and Assignment of Delinquent Real Estate Tax Liens

The City of Philadelphia recently announced a request for proposals to implement an online auction for the sale and assignment of some of the city’s delinquent real estate tax liens. The auction will allow third parties to bid on the tax liens, with the successful bidder assigned the lien from the city upon the purchaser’s payment at the conclusion of the auction. Title to the property against which the delinquent tax lien is sold will not be transferred. The third-party assignee would then pursue the collection of the delinquent taxes from the property owner.

Click here to read the full Duane Morris Alert, written by Brett Messinger and Louise Melchor.

Businesses Around the United States Being Targeted for Alleged Inaccessible Websites

While plaintiff’s lawyers have been busy the past two years filing lawsuits around the United States alleging violations of the Americans with Disabilities Act (ADA) related to physical barriers—including a wave of class action lawsuits against banks for inaccessible ATMs and against retailers for inaccessible point of sale devices (“POS devices”)—these lawyers are now turning their attention to company websites. Since May 2014, there has been a dramatic increase in the number of lawsuits and demand letters alleging that businesses have denied access to visually impaired customers by having websites that are inaccessible to them in some manner. Although the focus thus far has been primarily on website access for the visually impaired, website access issues may also arise for persons with mobility and hearing disabilities.

Click here to read the full Alert, written by Duane Morris partners Colin Knisely and Jonathan Petrakis.

U.S. Supreme Court Decision Answers Question Arising Out of Stern vs. Marshall Decision

In Executive Benefits Insurance Agency, petitioner vs. Peter H. Arkison, Chapter 7 Trustee, Case No. 12-1200, 573 U.S. __(2014) the United States Supreme Court ( Court) delivered its opinion as a follow up to its landmark decision in Stern v. Marshall. In Stern v. Marshall, the Court held that even though bankruptcy courts are statutorily authorized to enter final judgments on a class of bankruptcy related claims, Article III of the Constitution prohibits bankruptcy courts from finally adjudicating certain of those claims. Under Stern’s reasoning, the Constitution does not permit a bankruptcy court to enter final judgment on a bankruptcy related claim, the relevant statute does permit a bankruptcy court to issue proposed findings of fact and conclusions of law to be reviewed de novo by a federal district court. Because the District Court conducted the de novo review that petitioner demanded, the Court affirmed the judgment of the Court of Appeals upholding the District Court’s decision. The following information has been extracted from the syllabus prepared by the Reporter of Decisions and does not represent the actual written decision by the Court.

Continue reading “U.S. Supreme Court Decision Answers Question Arising Out of Stern vs. Marshall Decision”

Banks Previously Sued in Title III ADA Class Action Lawsuits Now Getting Sued Again in Second Wave of Accessibility Lawsuits

A Pittsburgh-based law firm, that has filed well over 100 class action lawsuits under Title III of the Americans with Disability Act (“ADA”) in federal District Courts throughout the country against banks on behalf of a plaintiff who alleged that the banks’ ATMs were inaccessible, is back at it and is filing more ADA Title III class actions against banks. The new ADA Title III class actions claim that the defendant banks’ branch locations are physically inaccessible to individuals in wheelchairs. In the past few weeks, the Carlson Lynch law firm has filed seven such class action lawsuits in the Federal District Court in Pittsburgh, all against banks the law firm had previously sued for alleged ATM accessibility violations. All of the new lawsuits involve the same plaintiff, Damian M. Zipf, who, according to the Complaints, is dependent upon a motorized wheelchair for mobility. Zipf alleges that he has been deterred from patronizing the bank branches because of certain accessibility barriers. In these newly filed wheelchair accessibility class actions, the plaintiff is alleging a variety of general ADA accessibility violations, including, but not limited to, inaccessible parking lots, handicap signs that are too low, inaccessible door hardware and entrances, and obstructed accessible routes. In each lawsuit, the Plaintiff claims to have visited a number of bank branches and has alleged specific ADA violations at each location.

Continue reading “Banks Previously Sued in Title III ADA Class Action Lawsuits Now Getting Sued Again in Second Wave of Accessibility Lawsuits”

© 2009- Duane Morris LLP. Duane Morris is a registered service mark of Duane Morris LLP.

The opinions expressed on this blog are those of the author and are not to be construed as legal advice.

Proudly powered by WordPress